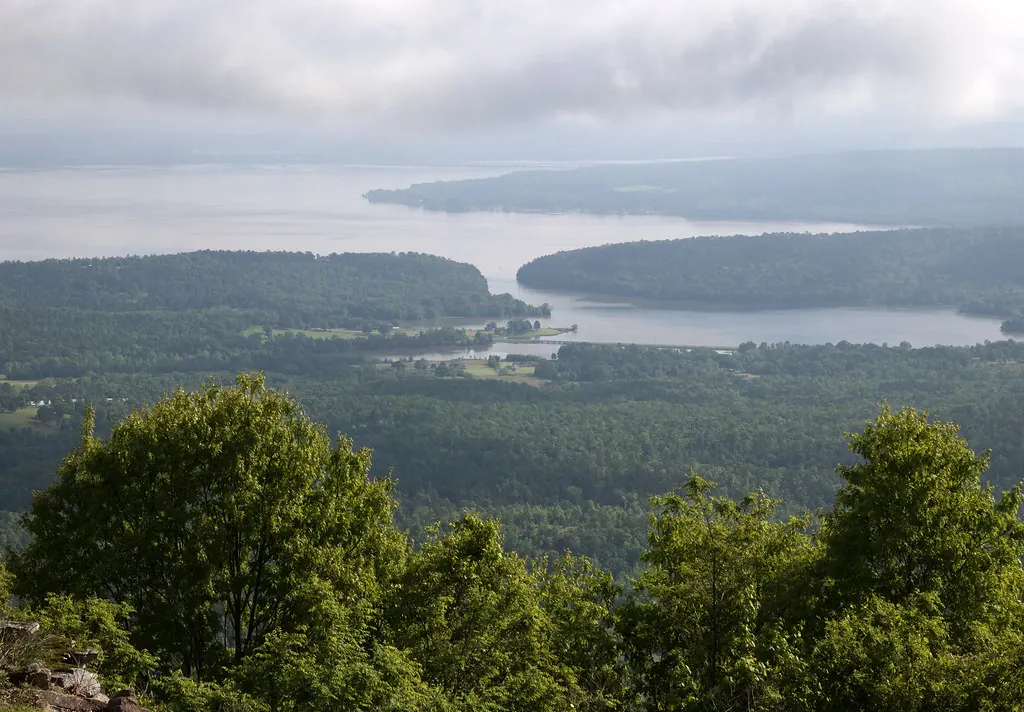
In spring 2019, the Arkansas River rose to record levels from Fort Smith through the River Valley and into Pine Bluff. Many owners learned for the first time that their homeowner policy didn’t cover rising water.
The basic rule
Standard homeowner and most commercial property policies exclude flood, meaning surface water, overflowing rivers and similar rising water. Flood coverage comes from the National Flood Insurance Program or a private flood policy. Wind, hail and rain entering through storm-created openings are typically covered under the property policy.
When both happen
A storm can tear off shingles and then flood the ground floor. Each policy pays for its own peril. Separating the two requires careful documentation:
- Mark and photograph the high-water line in each room.
- Document roof, siding and window damage that let rain in above the water line.
- Note where ceiling stains and wet insulation are, since rising water doesn’t wet ceilings.
Where appraisal fits
If the carrier accepts that wind caused some damage but disagrees on how much, appraisal can resolve the amount. If the carrier says the damage was all flood, that is a coverage dispute that may need an attorney.
Flash floods too
Flash flooding in hilly areas like Hot Springs and Fayetteville is still surface water under most policies. Water backing up through drains may be covered only with a specific endorsement.
Questions about your situation? Contact an Arkansas insurance appraiser for a free conversation.
General information, not legal advice. Policy wording and Arkansas law control.
Keep reading
How the Appraisal Clause Works in an Arkansas Policy
A plain-English walk through the appraisal condition found in most Arkansas property policies, and the mistakes that weaken it.
Labor Depreciation and ACV Payments in Arkansas
Your first check is usually actual cash value. How depreciation was calculated, including on labor, can change it by thousands.
Ice Storm Insurance Claims: Trees, Gutters and Roofs
Freezing rain is Arkansas’s quiet catastrophe. Here’s how ice storm claims work and where they get underpaid.