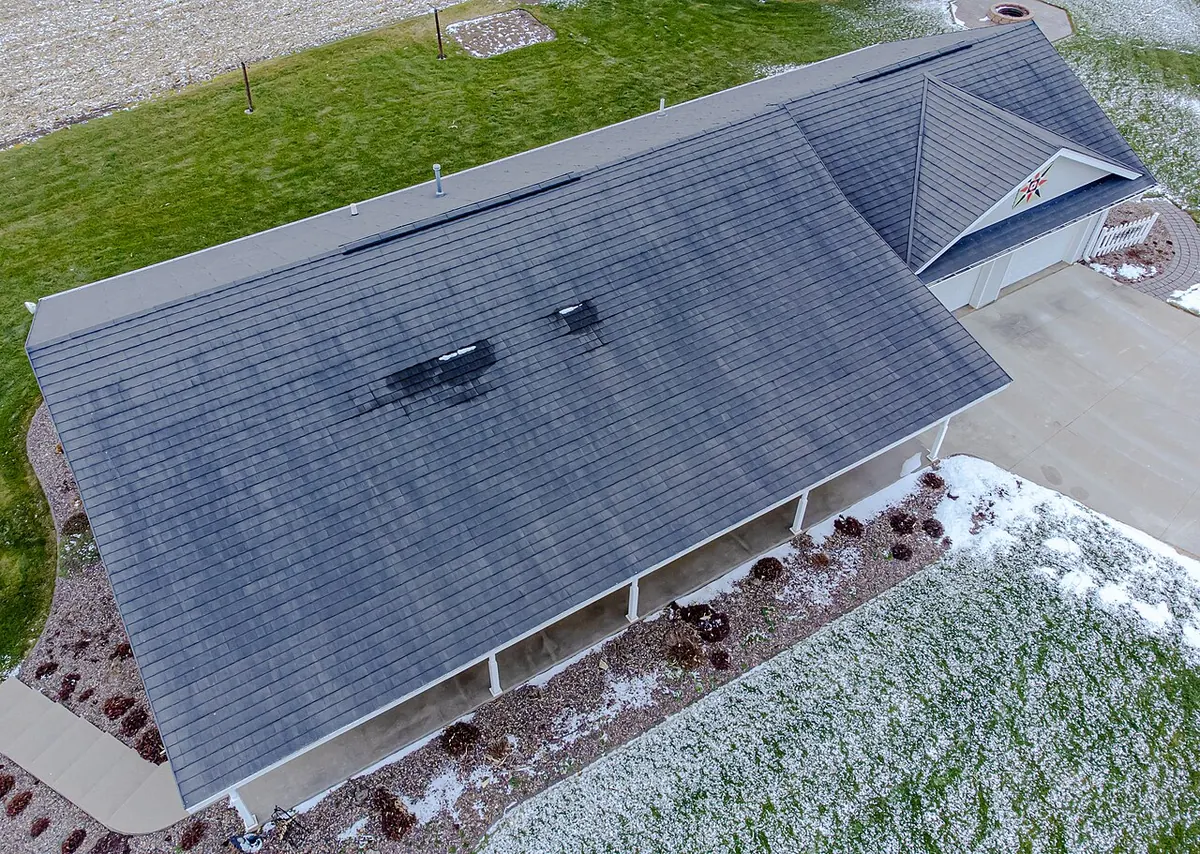
Most Arkansas homeowner and commercial property policies contain a short paragraph titled Appraisal. It says that if the two sides disagree on the amount of loss, either one can demand appraisal in writing. Each side then picks an appraiser, the two appraisers pick an umpire, and an agreement signed by any two of the three sets the amount. Appraisal clause representation means we fill the seat you get to choose.
What we do once you name us
- Scope the loss ourselves. We inspect, measure and photograph the property before we rely on anybody else’s figures.
- Price it for your market. Our estimate is line-item and priced for the property’s location, whether that is Bentonville, Jonesboro or a lake house on Greers Ferry.
- Compare line by line. We reconcile our scope with the carrier’s estimate and list every difference with the reason behind it.
- Negotiate with the other appraiser. Most panels settle the bulk of the items at this stage.
- Present the rest to the umpire. Anything still open goes to the umpire with photos, measurements and pricing support.
Timing matters
Policies usually give each side a short window, often 20 days, to name an appraiser after a written demand. Check your own policy’s wording. If the carrier demanded appraisal first, call us the day the letter arrives so the deadline doesn’t lapse while you look for help.
What appraisal won’t decide
An appraisal panel decides how much the covered damage costs. It generally does not decide whether a loss is covered at all, how a policy exclusion applies or whether an insurer acted in bad faith. Those are legal questions for an Arkansas attorney. We will tell you plainly if your dispute is about coverage rather than price.
Independence
We are paid by you, but an appraiser’s value to you depends on credibility with the umpire. We price what we can support with measurements, photos and market pricing, and we disclose any prior working relationship with the other appraiser or the proposed umpire.
Frequently asked questions
Can I be my own appraiser?
Some policies only require a ‘competent’ appraiser, but carriers and umpires expect line-item estimating skill. Most owners find a professional moves the panel further.
Who pays the umpire?
Under most Arkansas policy forms each side pays its own appraiser and splits the umpire’s fee equally. Read the appraisal paragraph in your policy to confirm.
Does appraisal end my claim?
It settles the amount of loss for the items submitted. Payment terms, deductibles and any coverage questions are still handled under the policy.
Related services
Homeowner Claim Appraisal
Independent valuation of disputed homeowner claims, from a single roof slope to a whole-house rebuild.Learn more
Commercial & HOA Claim Appraisal
Appraisal for stores, offices, warehouses, churches, apartments and HOA communities.Learn more