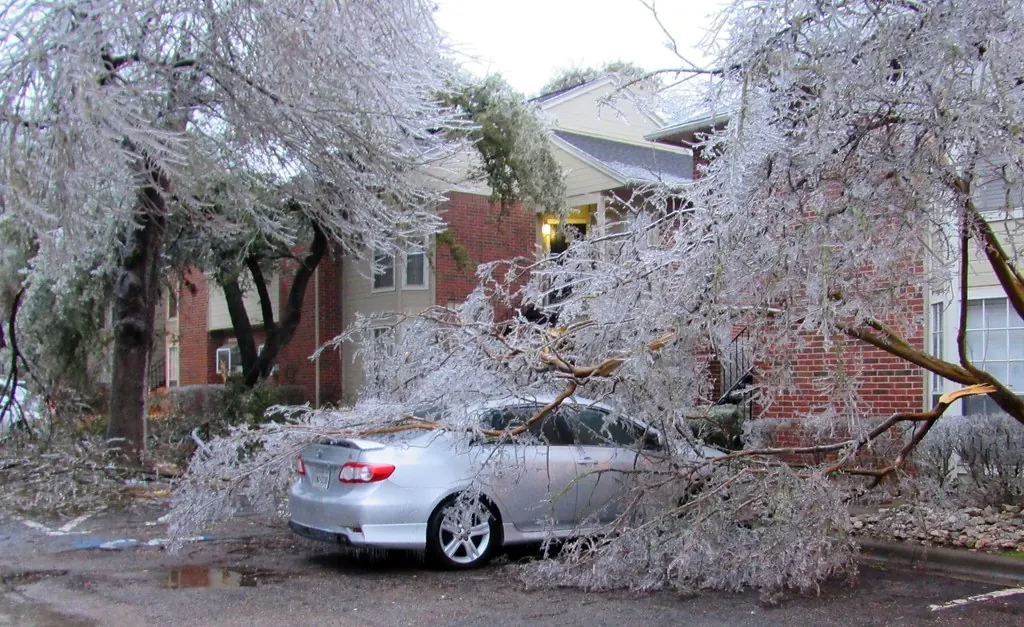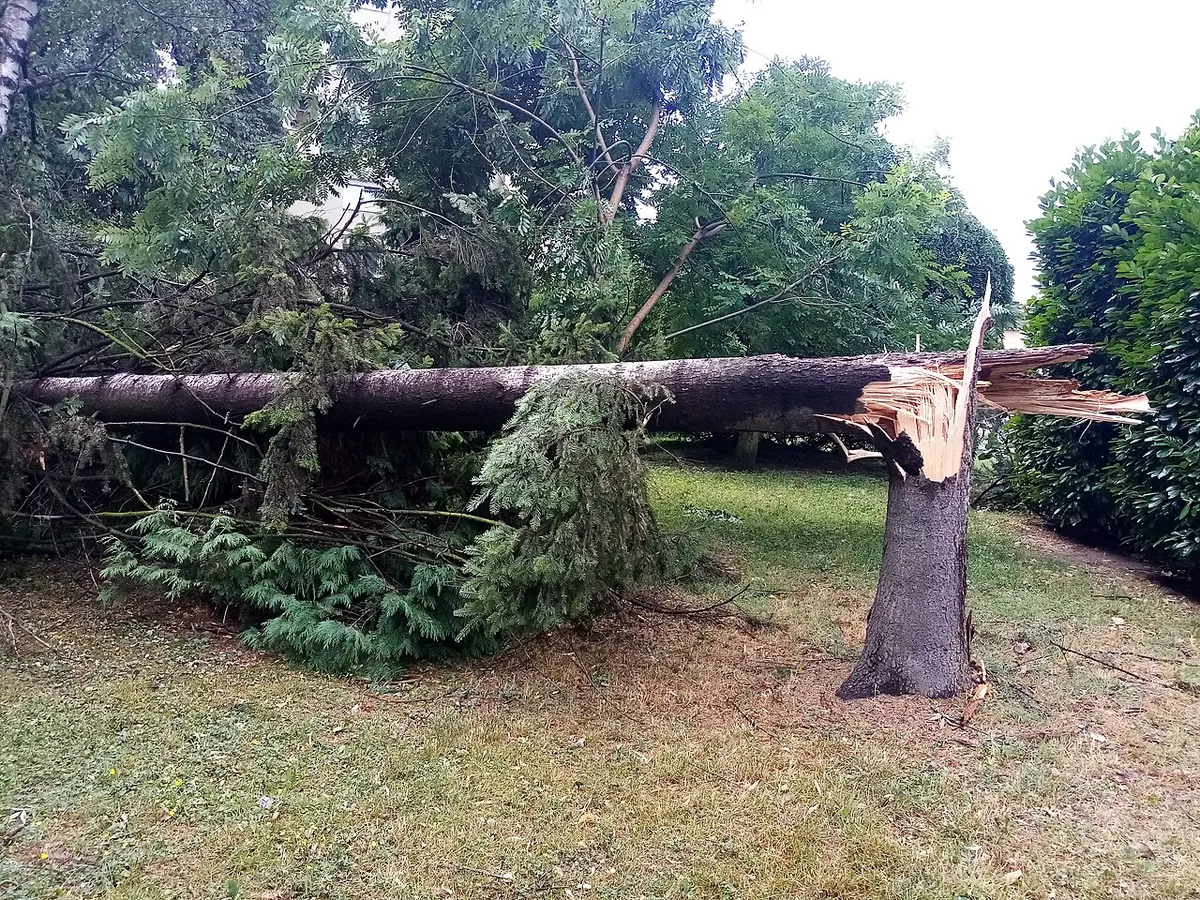
When a hurricane moves inland it weakens, but its wind field can still be strong enough to snap pines across the Gulf Coastal Plain from Texarkana to El Dorado and Crossett. Soaked ground makes trees easier to uproot, and a long-duration rain band finds every weak spot in a roof.
Typical remnant-storm claims
- Fallen trees on roofs and cars. Tree removal from the structure, roof framing repairs and interior water damage.
- Wind-driven rain. Water forced past window seals, siding and flashing. Coverage often depends on whether wind first created an opening, so the policy wording matters.
- Power outages. Spoiled food and, for businesses, possible business-income questions.
- Flooding. Rising water is generally excluded from homeowner policies and covered, if at all, by separate flood insurance. We help separate wind damage from flood damage so each policy pays its share.
Deductibles
Some policies apply a separate wind or hail deductible, sometimes a percentage of the dwelling limit, to storm losses. Read your declarations page and try our percentage deductible calculator to see what it means in dollars.
When appraisal fits
If the carrier accepted the wind damage but its estimate ignores framing repairs, interior water damage or the tree’s removal cost, appraisal can resolve the amount. If the carrier says the damage was flood rather than wind, that is a coverage question that may need an attorney.
Frequently asked questions
Is a hurricane deductible used in Arkansas?
Some policies sold in Arkansas use a wind/hail deductible rather than a named-storm deductible. Your declarations page shows which applies.
Are trees that fell without hitting anything covered?
Many policies cover removal only when a tree damages a covered structure or blocks access. Limits per tree are common.
What if wind and flood both damaged my home?
Each policy pays for its own peril. Careful documentation of where water came from is essential.
Related services
Water Damage Claim Appraisal
Burst pipes, appliance leaks and storm water inside the home, valued to a full and dry repair.Learn more
Fire & Smoke Damage Appraisal
Structure, smoke, soot and contents valued for a complete restoration, not a quick cleaning.Learn more