Water claims in Arkansas spike in two seasons: winter, when a hard freeze bursts pipes in crawl spaces and exterior walls, and spring, when storms drive rain through damaged roofs. The February 2021 cold wave burst pipes in homes and churches across the state, and many owners learned how quickly a slab-on-grade or pier-and-beam house can be soaked.
Where water estimates fall short
- Incomplete moisture mapping. Water travels under cabinets, through subfloors and into adjoining rooms. If the drying log wasn’t complete, the scope probably isn’t either.
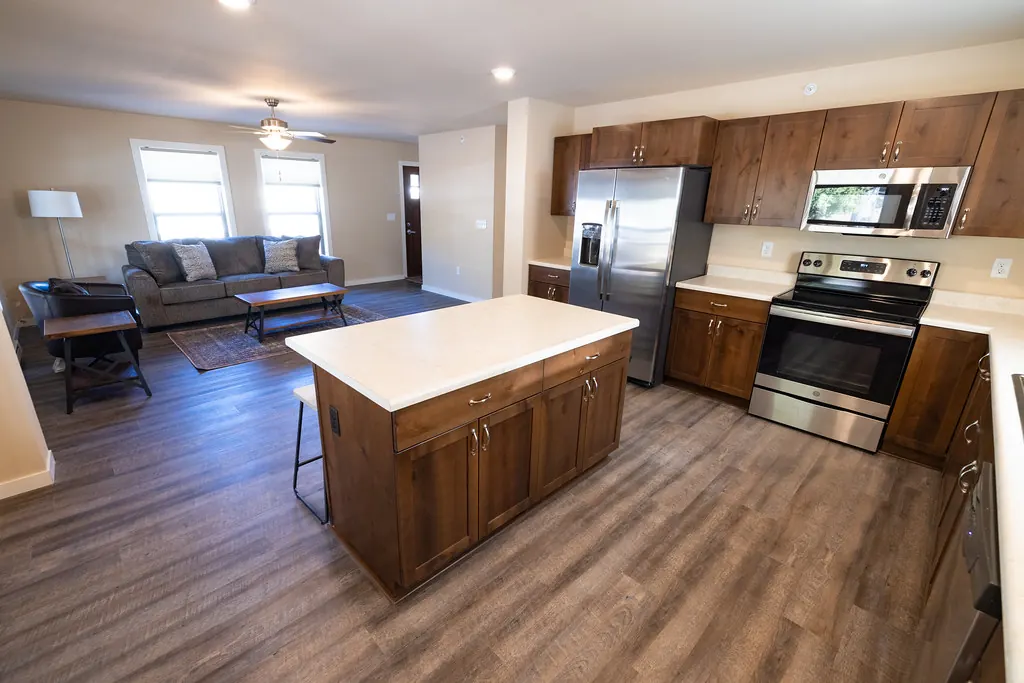
- Cabinets and countertops. Base cabinets swollen at the toe kick often can’t be dried. Removing them can damage countertops that are then unmatchable.
- Flooring continuity. Hardwood, laminate and LVP that runs room to room without a break.
- Crawl spaces. Wet insulation, vapor barriers and ductwork beneath pier-and-beam homes.
- Contents and living expense. Often the largest overlooked items after a major leak.
Coverage cautions
Most policies cover sudden and accidental discharge but exclude long-term seepage, flooding and some mold. The cause of the water matters. Appraisal can price the damage; whether a cause is covered is a separate question that may need legal advice.
What to keep
Save the failed part (supply line, valve, water heater), the mitigation company’s moisture readings and drying logs, and photos of every room before demolition. These records anchor the scope during appraisal.
Frequently asked questions
Is mold covered?
Many policies limit or exclude mold, sometimes with a small sublimit. Prompt drying is the best protection either way.
Should I let the mitigation company start before the adjuster visits?
Policies require reasonable steps to prevent further damage. Photograph everything, then mitigate.
The adjuster only approved drying, not repairs. Can appraisal help?
If coverage is accepted and the dispute is about scope and cost of repairs, appraisal can address it.
Related services
Fire & Smoke Damage Appraisal
Structure, smoke, soot and contents valued for a complete restoration, not a quick cleaning.Learn more
Ice Storm & Freeze Damage Appraisal
Arkansas’s signature winter peril: ice-loaded trees, collapsed gutters, roof damage and burst pipes.Learn more